Classification of Capital and Revenue Expenditures:
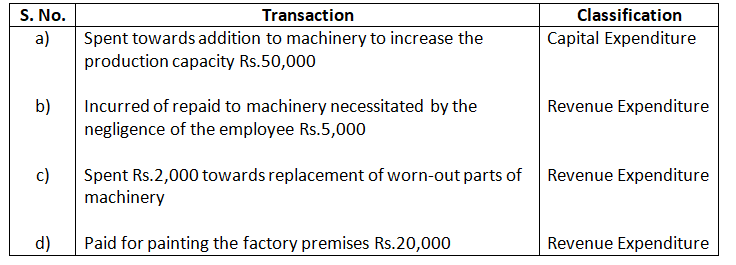
Q1. Classifying the following into Capital/Revenue Expenditure:
- Spent towards addition to machinery to increase the production capacity Rs.50,000.
- Incurred for repair to machinery, necessitated by the negligence of the employee Rs.5,000.
- Spent Rs.2,500 towards replacement of worn-out parts of machinery.
- Paid for painting the factory premises Rs.20,000.
Solution –
Q2. State with reason whether the following are capital or revenue in Expenditure:
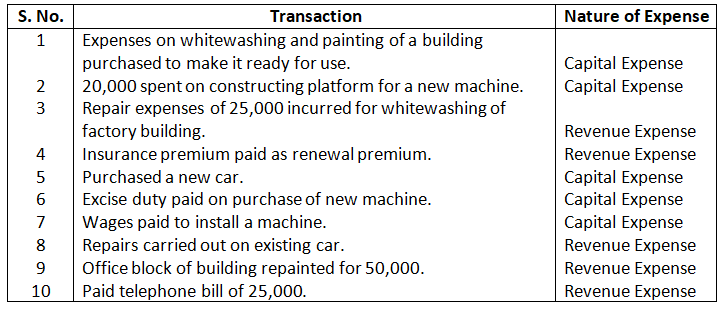
- Expenses on whitewashing and painting of a building purchased to make it ready for use.
- 20,000 spent on constructing platform for a new machine.
- Repair expenses of 25,000 incurred for whitewashing of factory building.
- Insurance premium paid as renewal premium.
- Purchased a new car.
- Wages paid to install a machine.
- Repairs carried out on existing car.
- Office block of building repainted for 50,000.
- Loss of stock by fire Rs.25,000.
Solution –
Trading Account:
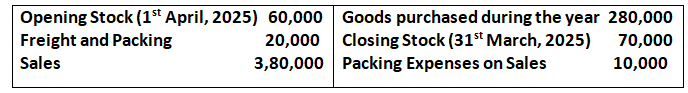
Q3. From the following information, determine Gross Profit for the year ended 31st March, 2026:
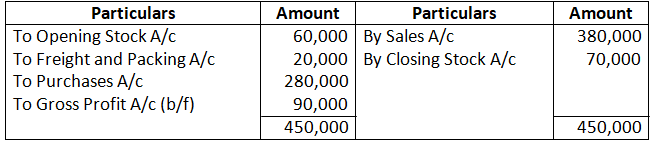
Solution – Trading Account
Dr As at March 31, 2026 Cr
Q4. Trading Account of Premier Trading Co. is given below:
Dr. Trading Account for the year ended 31st March, 2026 Cr.
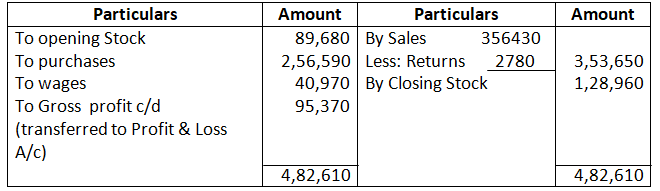
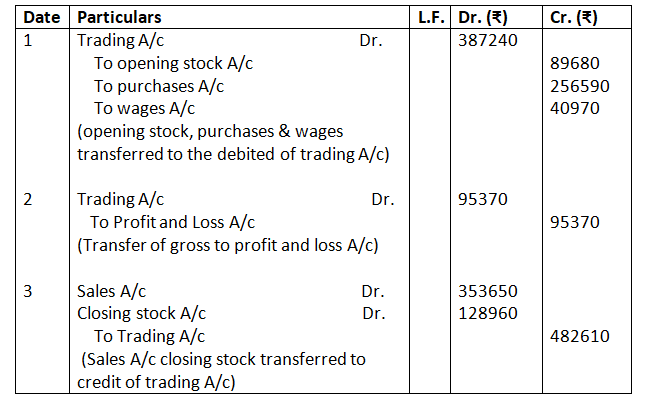
Pass Closing Journal entries on the basis of the above Trading Account. Also, transfer the Gross Profit to Profit & Loss Account.
Solution:-
Q5. Prepare Trading Account from the transactions given below:
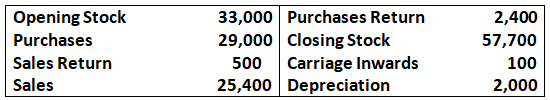
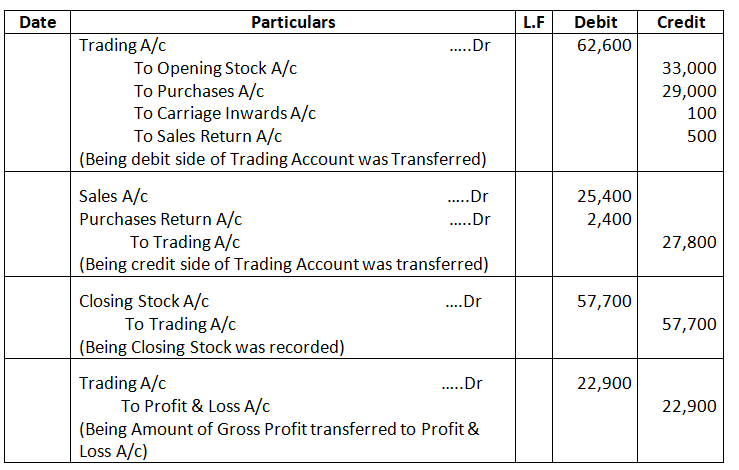
Also pass the Journal entries.
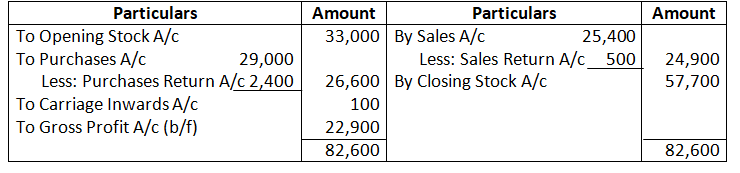
Solution – In the Books of……
Dr Trading Account for the Year Cr
Journal Entries
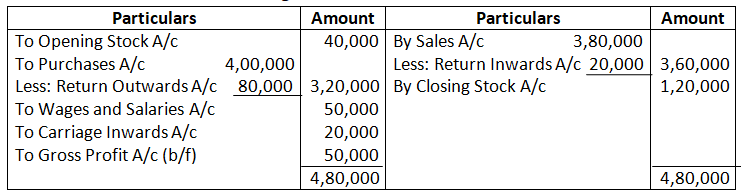
Q6. From the following information, prepare Trading Account for the year ended 31st March, 2026:
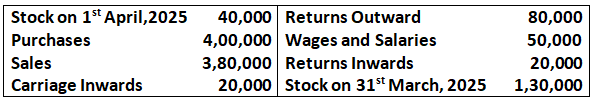
Net Realisable Value (Market Value) of stock as on 31st March, 2026 was 1,20,000.
Solution – In the Books of……
Dr Trading Account for the Year Cr
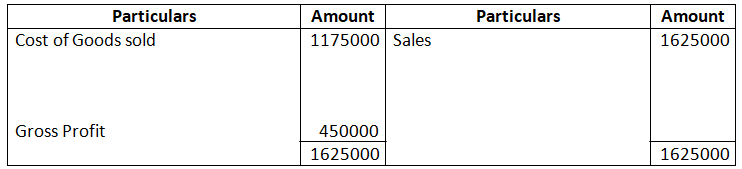
Q7. From the following information, prepare Trading Account for the year ended 31st March, 2026:
Cost of Goods Sold Rs.11,75,000
Opening Stock Rs.1,25,000
Wages Rs.17,500
Closing stock Rs.1,00,000
Sales Rs.16,25,000
Solution –
Dr Trading Account for the Year ended 31st March Cr
Q8. Following balances appear in the Trial Balance of a firm as on 31st March, 2026:
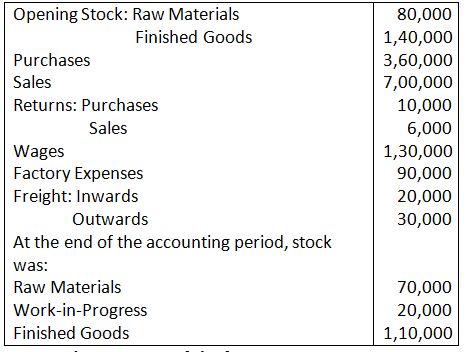
Prepare Trading Account of the firm.
Solution – Financial Statement of…..
Dr Trading Account for the Year ended March 31, 2026 Cr
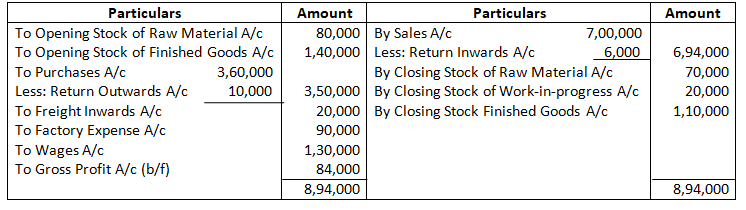
Q9. From the following information, prepare Trading Account for the year ended 31st March, 2026:
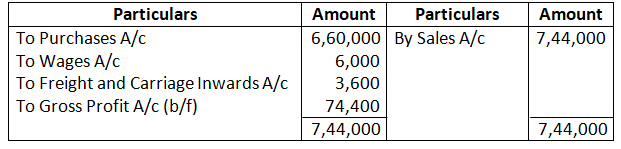
Adjusted Purchases 6,60,000; Sales 7, 44,000; Closing Stock 50,400; Freight and Carriage Inwards 3,600; Wages 6,000; Freight and Cartage Outwards 2,000
Solution – In the Books of…..
Dr Trading Account for the Year ended March 31, 2026 Cr
Calculate of Gross Profit, Opening Stock, Closing Stock and cost of goods sold
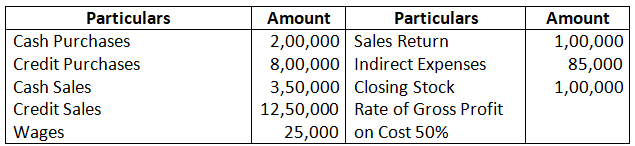
Q10. Calculate Opening Stock from the following information:
Solution:-
Calculate of opening stock
Net purchases = Cash purchases + Credit Purchases – Purchase return
= 2,00,000 + 8,000 – 0
= Rs.10,00,000
Net Sales = Cash sales + Credit Sales – Sales Return
= 3,50,000 + 12,50,000 – 1,00,000
= 15,00,000
Cost of Goods Sold = Opening stock + Net purchases + wages – closing stock
10,00,000 = opening stock = 10,00,000 + 2500 – 1,00,000
Opening stock = 10,00,000 – 10,00,000 – 2500 + 1,00,000
Opening stock = 75,000
Working Notes:-
Calculation of cost of goods sold
Gross Profit = Net Sales – cost of Goods Sold
50x/100 = 1500,000 – x
X + 50x/100 = 15,00,000
150x/100 = 15,00,000
X = 15,00,000 x 100 /150
Cost of goods sold = Rs.10,00,000
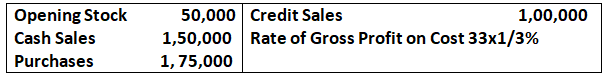
Q11. Calculate Closing Stock from the following details:
Solution –
Total Sales = Cash Sales + Credit Sales
= 1,50,000 + 1,00,000
= 2,50,000
Cost Assume = 100
Gross Profit of Cost = 33 x 1/3 %
Selling Price = 100+ 33 x 1/33 %
Selling Price = 133 x 1/3 %
Formula of Profit on Selling Price = Profit / Selling Price x 100
= 33 x 1/3 / 133 x 1/3 x 100
= 100/3 / 400/3 x 100
= 100/3 x 3/400 x100
= 25%
Gross Profit = 2,50,000 x 25% = 62,500
Cost of Goods Sold = Sales – Gross Profit
= 2,50,000 – 62500
= 187,500
Cost of Goods Sold = Opening Stock + Purchase – Closing Stock
187500 = 50,000 + 175000 – Closing Stock
187500 = 225,000 – Closing Stock
Closing Stock = 225000 – 187500
= 37500
Q12. Ascertain Gross Profit from the following information:
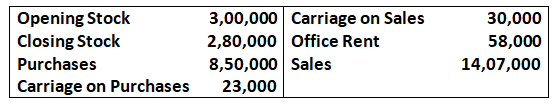
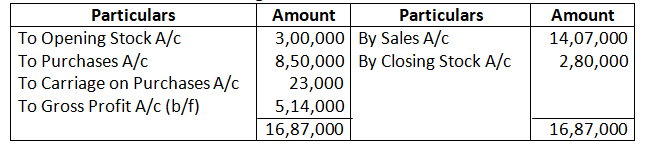
Solution – In the Books of……
Dr Trading Account for the Year Cr
Q13. Calculate Gross Profit when:
Total Purchases During the year are Rs.20,00,000;
Return Outward : Rs.50,000
Direct Expenses : Rs.1,50,000
2/3rd goods are sold for Rs.15,25,000.
Solution:-
Calculation of cost of Goods sold
Total purchases during the year = Rs.20,00,000
Return outward = Rs.50,000
Net purchases = Rs.20,00,000 – 50,000
= 19,50,000
Direct expenses = 150,000
Total cost of Goods Available for sale:
Net purchases + Direct expenses
19,50,000 + 1,50,000
= 21,00,000
Thus, cost of goods sold for 2/3rd goods sold
Cost of Goods sold = 2/3 x 21,00,000
= Rs.14,00,000
Calculation of Gross Profit
Gross profit = Sales – Cost of Goods sold
= 15,25,000 – 1400000
= 1,25,000
Q14. (a) Net Sales for the year ended 31st March, 2026 is Rs.4,50,000. If Gross Profit is 30% on Sales, find Cost of Goods Sold.
(b) Net Sales for the year ended 31st March, 2026 is Rs.4,50,000. If Gross Profit is 25% of cost, find Gross Profit and cost of Goods Sold.
Solution:-
Case – (a)
Given : Net Sales = RS.4,50,000
Gross Profit = 30% on sales
Cost of Goods Sold = ?
Gross Profit = 30% of sales
= 30/100 x 4,50,000
= 1,35,000
Cost of Goods sold = Net Sales – Gross Profit
= 4,50,000 – 1,35,000
= 3,15,000
Case – (b)
Calculate of cost of Goods sold
Given : Net sales = Rs.4,50,000
Gross profit = 25% of cost
Let cost of goods sold be Rs.x
Gross profit = net sales – cost of goods sold
25/100x = 4,50,000 – x
25x/100 + x = 4,50,000
125x /100 = 4,50,000
Cost of goods sold (x) = 4,50,000 x 100/125
= Rs.3,60,000
Calculate of Gross Profit
Gross profit = Net Sales – Cost of Goods Sold
= 4,50,000 – 3,60,000
= 90,000
Q15. Calculate Net Sales and Gross Profit from the following information:
Cost of Goods Sold : Rs.2,50,000%, Gross Profit 20% on Sales.
Solution:-
Calculation of Net Sales
Given : cost of Goods Sold = Rs.2,50,000
Gross Profit = 20% on sales
Let the Net sales be Rs.x
Gross Profit = Net Sales – Cost of goods sold
20x/100 = x – 2,50,000
X – 20x/1000 = 2,50,000
100x – 20x /100 = 2,50,000
80x/100 = 2,50,000
Net Sales (x) = 2,50,000 x 100 / 80
= 312500
Calculate of Gross Profit
Gross Profit = Net Sales – Cost of Goods sold
= 3,12,500 – 2,50,000
= 62,500
Q16. From the following prepare Profit and Loss Account of Gurman as it would appear in the 1st year that ended 31st March, 2026:
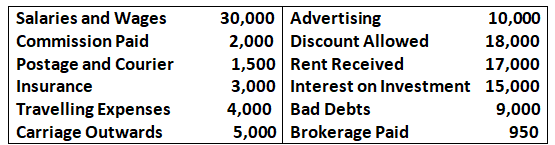
The Gross Profit was 45% of Sales, which amounted to 6, 50,000.
Also pass the Journal entries.
Solution – In the Books of Sohan Lal
Dr Profit and Loss Account for the Year ended March 31, 2026 Cr
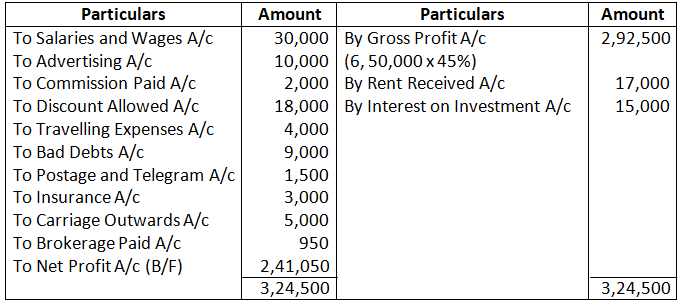
Working Note 1:-
Gross Profit = Sales x Percentage
= 6, 50,000 x 45%
= 2, 92,500
Q17. From the following information, prepare Profit and Loss Account for the year ended 31st March, 2025:
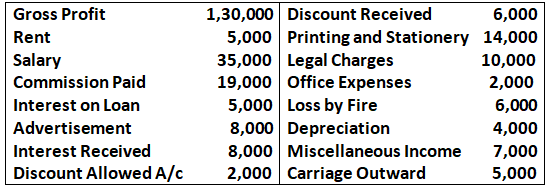
Solution – In the Books of…..
Dr Profit and Loss Account for the Year ended March 31, 2026 Cr
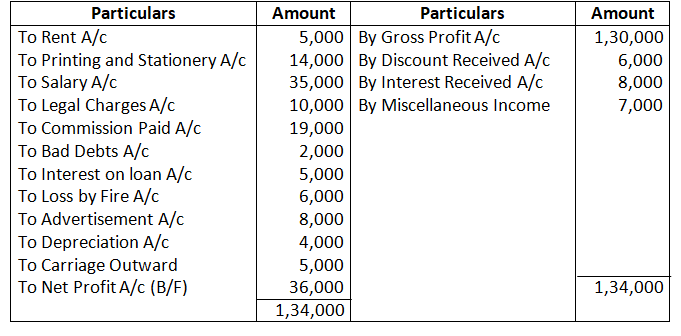
Calculation of Operation Profit
Q18. From the following figures, calculated Operating Profit:
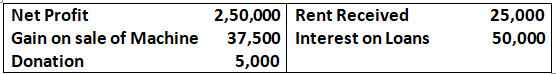
Preparation of Profit & Loss Account showing Operating Profit separately
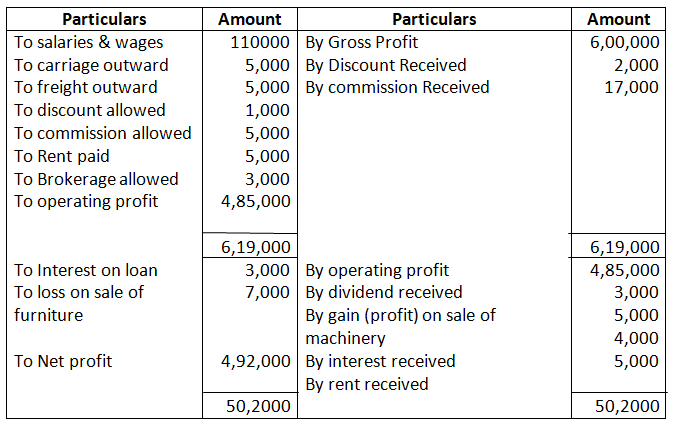
Q19. From the following information, prepare Profit & Loss Account showing Operating Profit separately in the account itself of Manoj Traders for the year ending on 31st March, 2026:
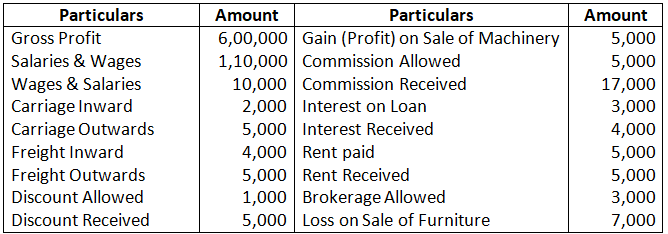
Solution:-
Dr. profit and loss A/c for the year ended 31st March Cr.
(i) Sales Book total not posted to Sales Account →
This means one side (credit side) of the entry is missing.
This will affect the Trial Balance.
(ii) Installation charges wrongly debited to Repairs A/c instead of Machinery A/c →
Both debit and credit have been recorded, but in the wrong account.
Does not affect Trial Balance.
(iii) Drawings treated as Debtor →
Again, both sides recorded but in wrong accounts.
Does not affect Trial Balance.
(iv) Repairs wrongly debited to Building A/c →
Wrong account but both sides recorded.
Does not affect Trial Balance.
Only error (i) will affect the Trial Balance.
Trading and Profit and Loss Account
Q20. Prepare Trading and Profit & Loss Account of Vijay for the year ended 31st March, 2026 from the following information taken from his Trial Balance:
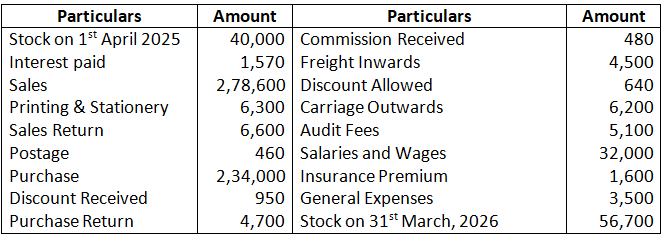
Solution –
Balance Sheet:
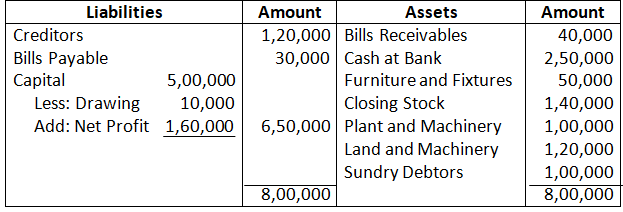
Q21. From the following particulars, prepare Balance Sheet as at 31st March, 2026:
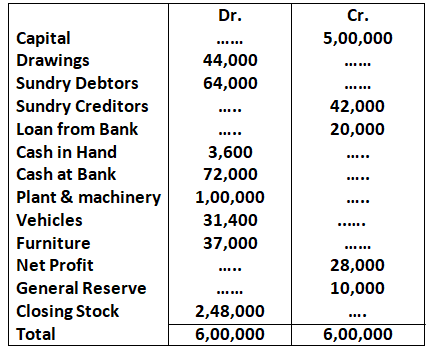
Solution – Balance Sheet
As on 31 March 2026
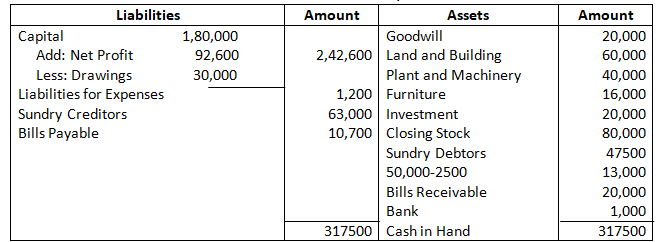
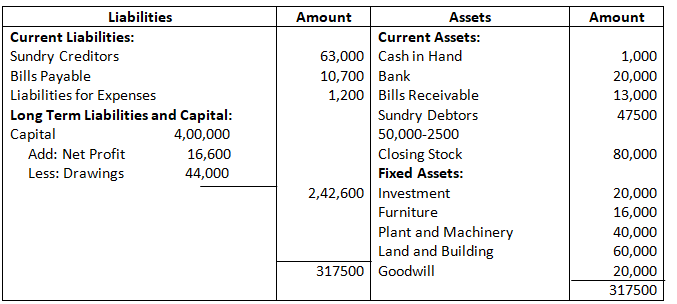
Q22. From the following information, prepare Balance Sheet of a trader as at 31st March, 2026 arranging the assets and liabilities – (i) in order of permanence and (ii) in order of liquidity:
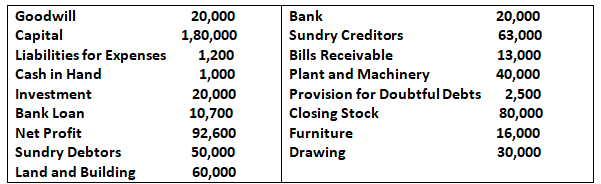
Solution – in order Permanence Balance Sheet
As on March 31, 2026
In order of Liquidity Balance Sheet
As on March 31 2026
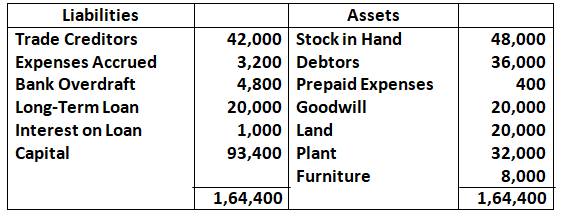
Q23. From the Balance Sheet given below, calculate:
- Fixed Assets
- Current Assets
- Current Liabilities
- Working Capital
Balance Sheet as at 31st March, 2026
Solution –
- Fixed Assets = Goodwill + Land + Plant + Furniture
= 20,000 + 20,000 + 32,000 + 8,000
= 80,000
II. Current Assets = Stock in Hand + Debtors + Prepaid Expenses
= 48,000 + 36,000 + 400
= 84,400
III. Current Liabilities = Trade Creditors + Expenses Accrued + Bank Overdraft + Interest on loan
= 42,000 + 3,200 + 4,800 + 1,000
= 51,000
IV. Working Capital = Current Assets – Current Liabilities
= 84,400 – 51,000
= 33,400
Preparation of Final Accounts:
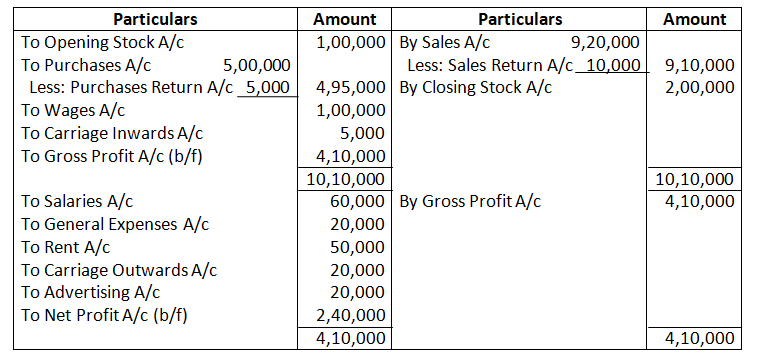
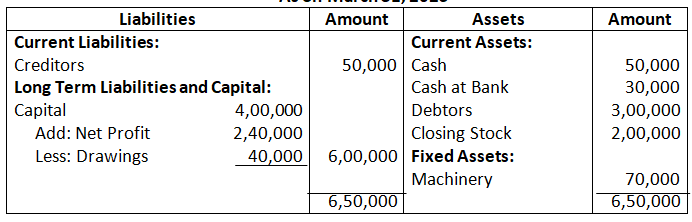
Q24. Prepare Trading and Profit and Loss Account and Balance Sheet of Jagat as at 31st March, 2025 from the following balances:
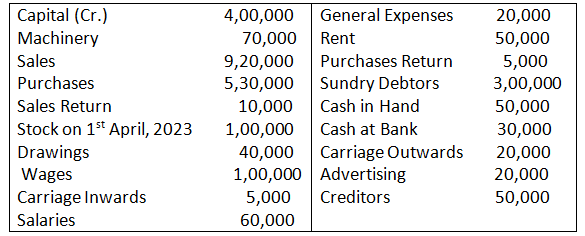
Closing Stock was valued at 2, 00,000
Solution – In the Books of Jagat Shah
Dr Trading and Profit & Loss Account for the Year ended March 31, 2025 Cr
Balance Sheet
As on March 31, 2025
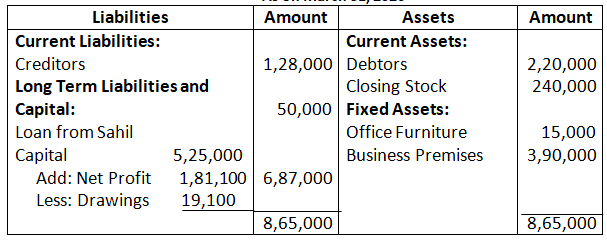
Q25. The following are the balances as on 31st March, 2026 extracted from the books of Dass:
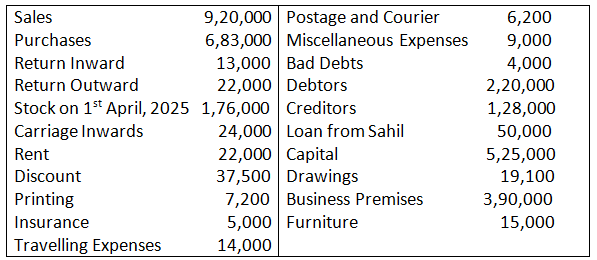
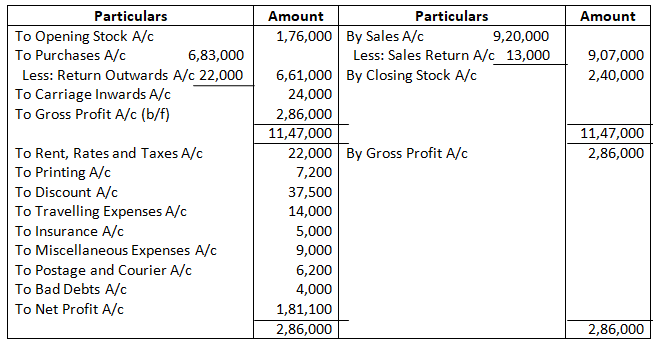
The stock on 31st March, 2026 was valued at 2,40,000.
You are required to prepare Trading Account, Profit and Loss Account and Balance Sheet as at 31st March, 2026.
Solution – In the Books of Bhagwan Dass
Dr Trading and Profit & Loss Account for the Year ended March 31, 2026 Cr
Balance Sheet
As on March 31, 2026
Q26. From the following balances of Anand, prepare Trading Account, Profit and Loss Account and Balance Sheet as at 31st March, 2026:
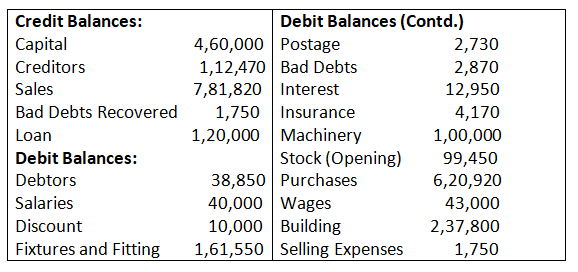
Value of goods on hand (31st March, 2026) was 1,43,000.
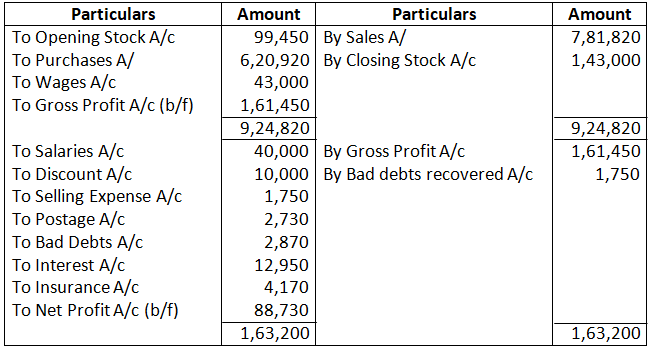
Solution – In the Books of Ananda
Dr Trading and Profit & Loss Account for the Year ended March 31, 2026 Cr
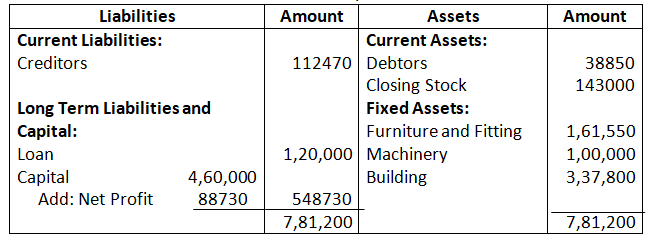
Balance Sheet
As on March 31, 2026
Q27. From the following balances, prepare Trading and Profit and Loss Account for the year ending 31st March, 2026 and the Balance Sheet as on that date:
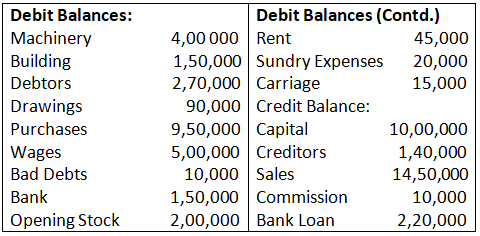
Closing Stock was of 70,000 but its net realisable value (market value) is 60,000
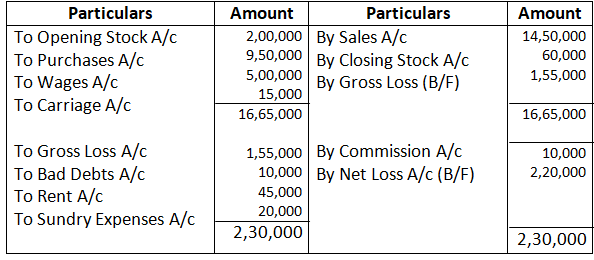
Solution – In the Books of……
Dr Trading and Profit & Loss Account as on Cr
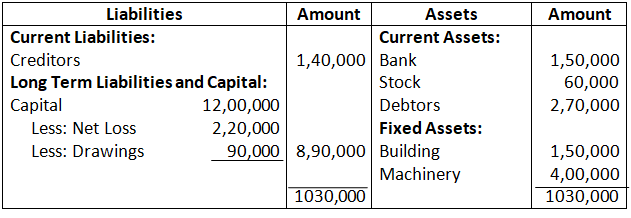
Balance Sheet
As on March 31, 2026
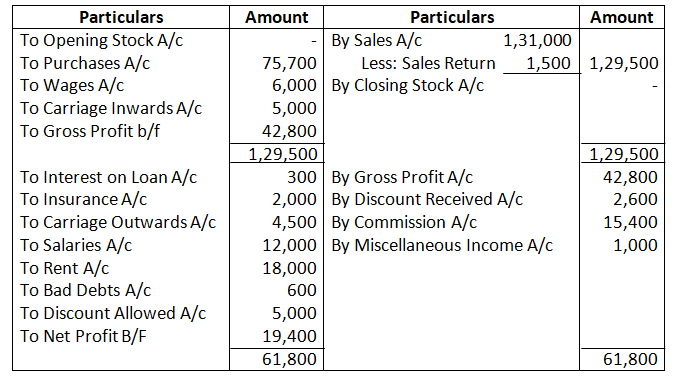
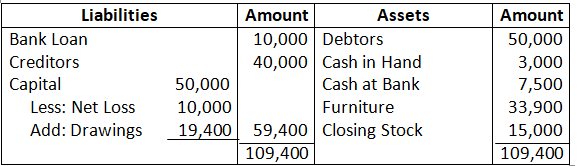
Q28. The following is the Trial Balance of Raman as at 31st March, 2026:
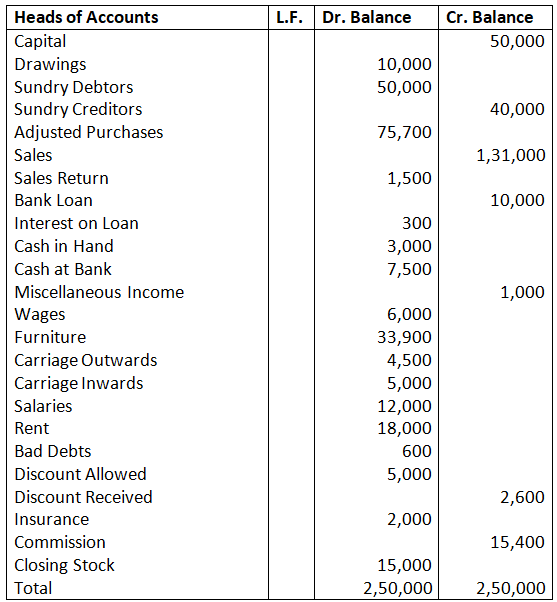
Prepare Trading and Profit and Loss Account for the year ending on 31st March, 2026 and Balance Sheet as on that date.
Solution – In the Books of …
Dr Trading and Profit & Loss Account for the year ended March 31, 2026 Cr
Balance Sheet
As on March 31, 2025
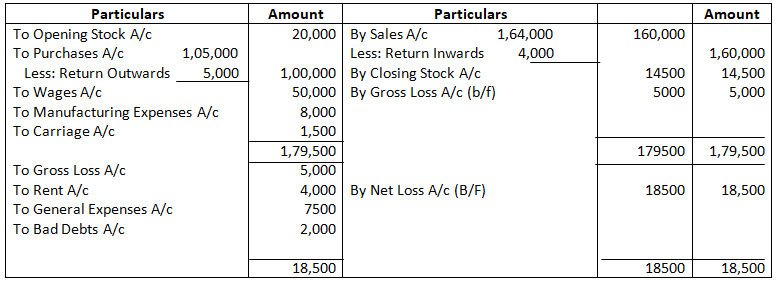
Q29. From the following balances as on 31st March, 2026, prepare Trading and Profit and Loss Account and Balance Sheet:
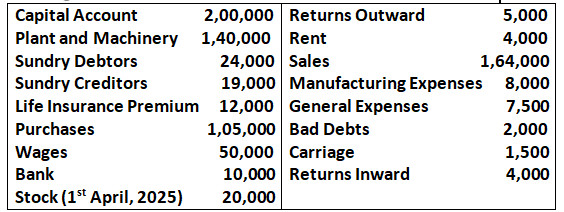
Closing Stock on 31st March, 2026 was valued at 14,500.
Solution – In the Books of
Dr Trading and Profit & Loss Account for the year ended March 31, 2026 Cr
Balance Sheet
As on March 31, 2026
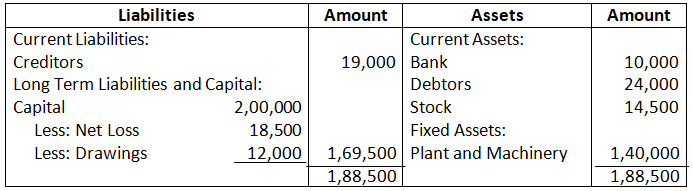
Q30. Trial Balance of Chatter on 31st March, 2026 revealed the following balance:
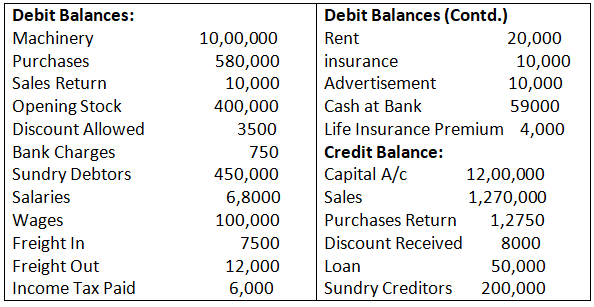
Stock on 31st March, 2026 was 350,000 at cost and its net realisable value (market value) was 4,00,000
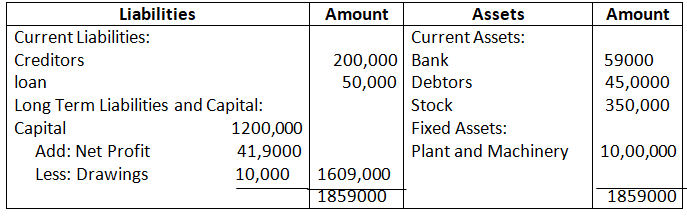
Prepare Trading and Profit and Loss Account for the year ended 31st March, 2026 and Balance Sheet as at that date.
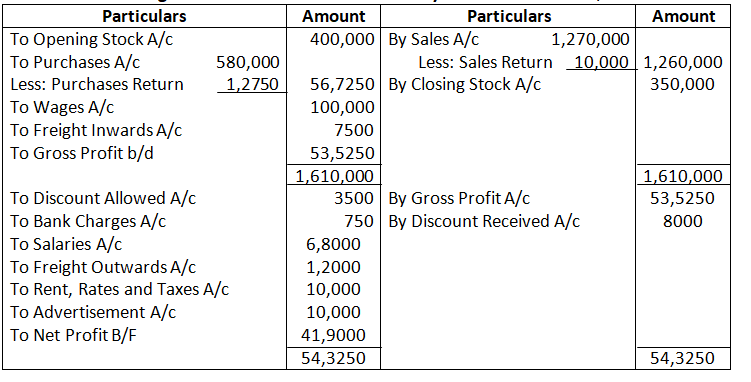
Solution – In the Books of Chatter Sen
Dr Trading and Profit & Loss Account for the year ended March 31, 2026 Cr
Balance Sheet
As on March 31, 2026
Q31. Prepare Trial Balance, Trading and Profit and Loss Account for the year ended 31st March, 2026 and Balance Sheet of the Raja Trading Company as at that date, from the following extracts of Ledger balances:
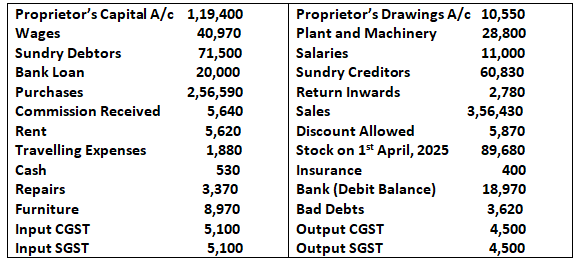
Stock in Hand on 31st March, 2026 was valued at 1, 28,960.
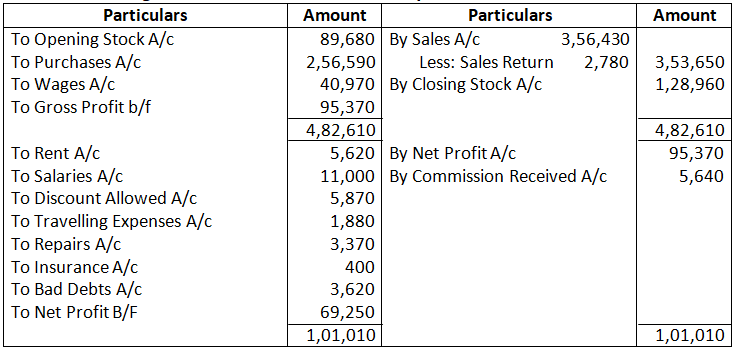
Solution – In the Books of
Dr Trading and Profit & Loss Account for the year ended March 31, 2026 Cr
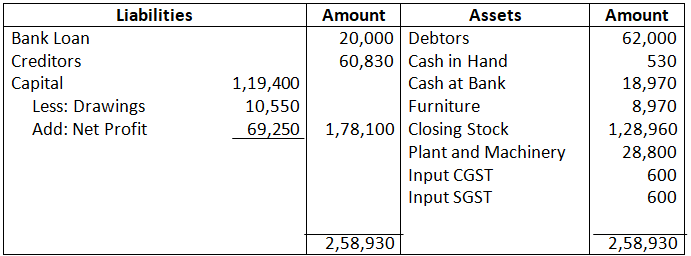
Balance Sheet
As on March 31, 2026
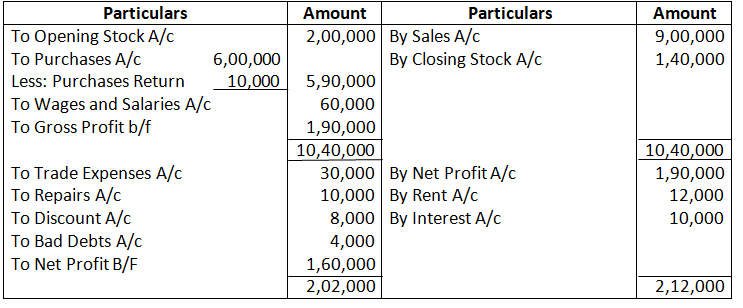
Q32. From the following Trial Balance, Prepare Trading and Profit and Loss Account for the year ended 31st March,2026 and Balance Sheet as at that date:
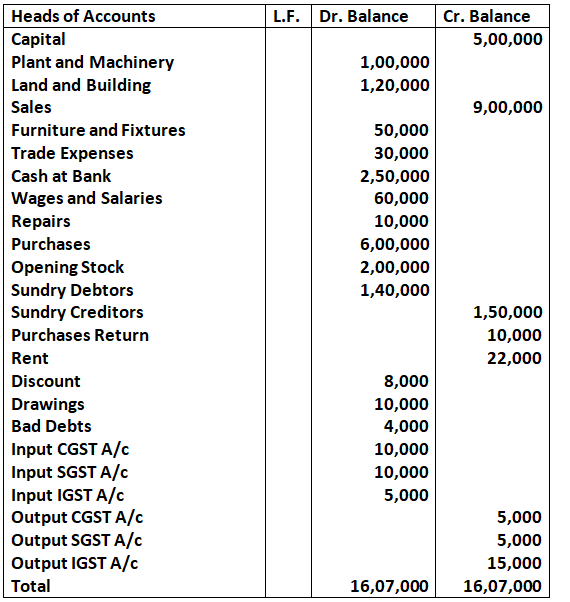
The stock on 31st March, 2026 was valued at 1,40,000.
Solution in the Books of
Dr Trading and Profit & Loss Account for the year ended March 31, 2026 Cr
Balance Sheet
As on March 31, 2026